How you make money
Cash flow
In-place NNN income from day one, no lease-up
The building is 100% leased to 1-800 PackRat on a 10-year triple-net term at $17.50 PSF. The tenant pays taxes, insurance, and maintenance, and rent escalates 3.5% each year. Distributions are quarterly as available.
4.6%
Annual cash yield
Quarterly
Distributions
Equity growth
Below-replacement basis with a 110 bps cap cushion
Entry is at the seller's development cost of $276/SF, roughly 33% below the $410/SF Class A comp average, at a 6.2% going-in cap versus a 5.12% comp-set average. The plan targets a sale around year three.
2.2x
Equity multiple
31.5%
Projected IRR
3 years
Hold period
Sale
Exit strategy
Tax efficiency
Each $1 invested allocated ~$1.56 of 2026 taxable loss
The contemplated structure concentrates first-year tax attributes among Class A equity, allocating roughly $1.56 of bonus depreciation per $1 invested on 2026 returns. Consult your own tax advisor.
156%
Taxable loss per $1 invested (Y1)
How the deal works
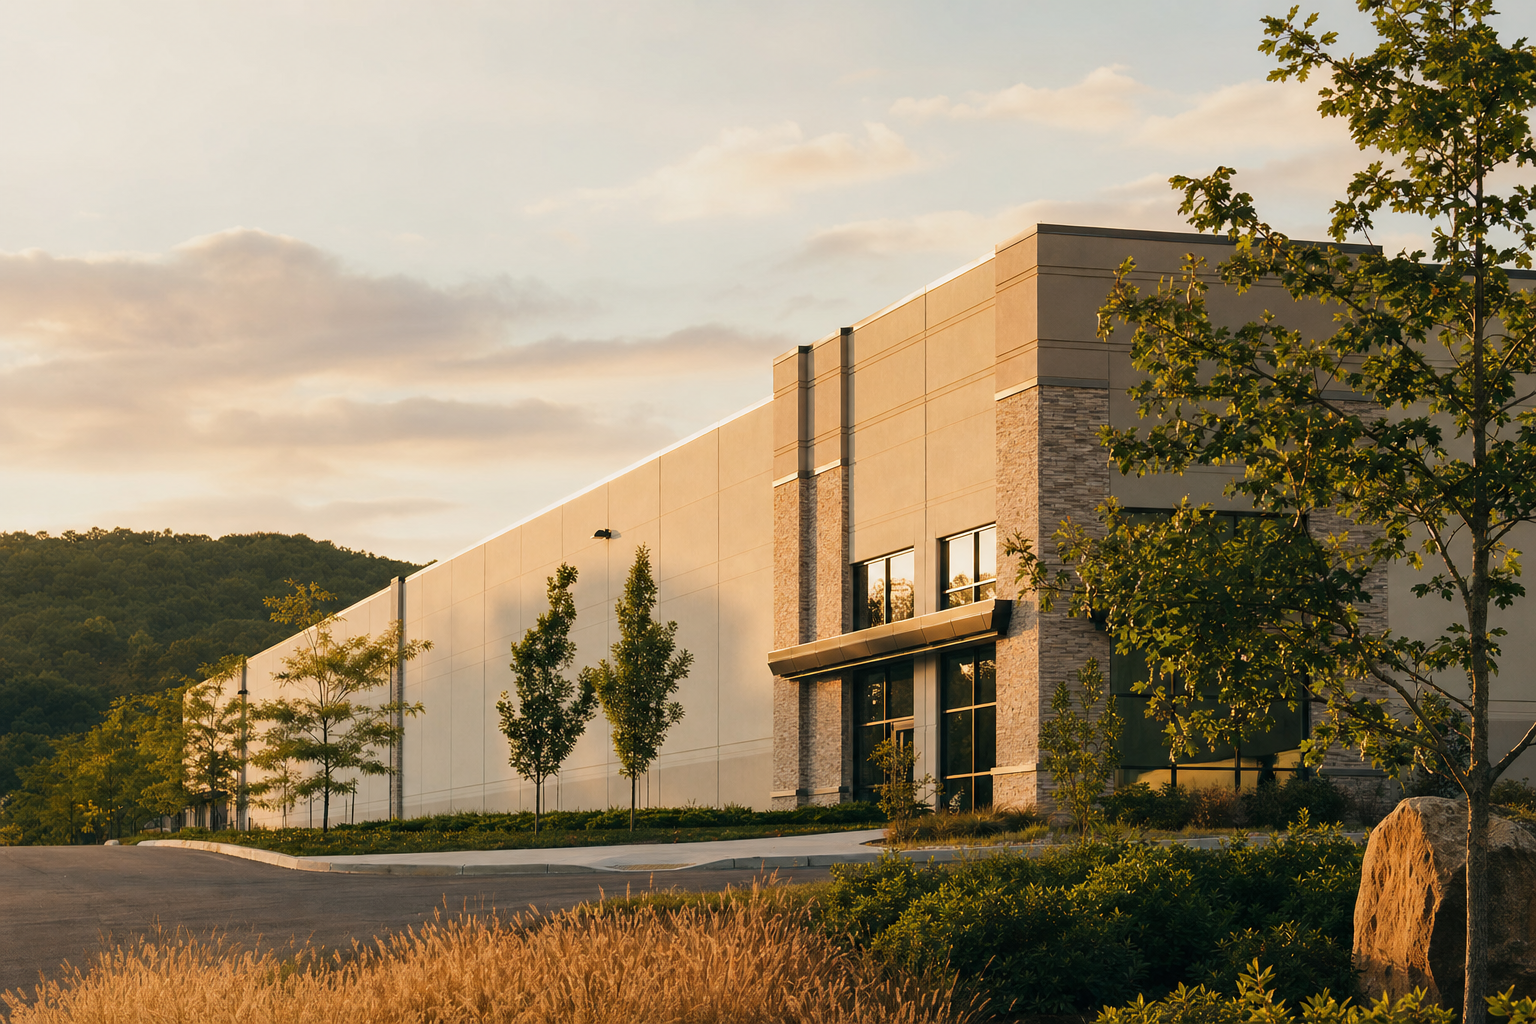
The deal acquires 20 Dock Road, a 2026-built 118,200 SF distribution warehouse in land-constrained Morris County, fully leased on a triple-net basis to 1-800 PackRat for 10 years. Income runs from day one with no lease-up or renovation, and the tenant covers taxes, insurance, and maintenance while rent grows 3.5% a year. Entry is at the seller's $276/SF development cost, about 33% below recent Class A sales, targeting a roughly 2.2x return over a three-year hold.
In-place NNN income the day the deal closes
The building is 100% leased to 1-800 PackRat on a 10-year triple-net term at $17.50 PSF, or about $2.1M a year. The tenant pays taxes, insurance, and maintenance, rent escalates 3.5% annually, and the landlord is responsible only for roof and structure.
Bought at $276/SF, about 33% below Class A comps
Acquisition at the seller's development cost basis sits 33% below the $410/SF average of recent Northern NJ Class A trades, at a 6.2% going-in cap versus a 5.12% comp-set average. The property would need to sell at a 6.5% cap just to return investor principal.
Land-constrained I-80 / I-287 location near NYC
The property sits at the I-80 / I-287 interchange, roughly 35 miles from Manhattan and 25 miles from Port Newark-Elizabeth, with direct I-80 access in under three minutes. Morris County is built-out with restrictive zoning and limited new supply.
Structure concentrates 2026 tax losses in equity
The financial structure allocates roughly $1.56 of taxable loss per $1 of Class A equity in 2026 through bonus depreciation. For a high-income investor this can materially reduce the current-year tax bill.
About the sponsor
1,065,000+ SF
Real property owned or managed
$270MM
Portfolio value
40+ yrs
Operating history
Bristol Capital Corporation is a full-service commercial real estate firm founded in August 1986, focused on the acquisition, development, and management of commercial assets across industrial, flex, office, self-storage, senior housing, and land.
Dave Sislen
President & Managing Director, Bristol Capital Corp.
Active in real estate since 1978; President of BCC since 1986. Previously SVP at CRI Inc., where he developed, acquired, and syndicated over $650M of commercial real estate. MBA in Finance and Accounting, University of Chicago; adjunct faculty at Georgetown's McDonough School of Business.
Gareth Taylor
Founder & President, Zippy Shell Inc.
Grew Zippy Shell in the US from startup to over $250M in revenue since 2010. Raised over $500M in growth capital for business expansion. MBA from Kellogg; former Director at Marakon Associates.
John Conley
VP, Zippy Shell · Founder, Shepherd Realty Capital
Has managed the acquisition and development of over $800M of real estate. Former Manager of Acquisitions and Equity at Jefferson Apartment Group.
Jay Stewart
VP, Zippy Shell · Principal, Shepherd Realty Capital
Responsible for evaluation, acquisition, financing, development, and asset management. Former Project Manager in Development at Boston Properties.
What you should know
What are the risks?
- Single-tenant concentration: all cash flow depends on one occupant, a default or non-renewal would take occupancy to zero.
- Refinance and interest-rate risk: the $22.0M senior loan must be refinanced or the asset sold around year three into an unknown rate environment.
- Cost of preferred and subordinated capital: preferred equity accrues at a 14.5% total rate and is paid ahead of Class A equity.
- Exit cap-rate expansion: a wider exit cap rate would compress residual value and the projected 2.2x multiple.
- Basis and replacement cost: industrial pricing has run ahead of fundamentals in several Northern NJ submarkets.
- Supply pipeline: roughly 898,000 SF of competing Class A space is available or planned in the submarket.
Who is the tenant and how strong is the lease?
1-800 PackRat, a wholly owned subsidiary of Zippy Shell Inc, is the second-largest provider of portable moving and storage in the US, operating 70+ warehouses and 3.2M SF of space. The lease is a 10-year corporate-guaranteed triple-net obligation.
What protects against a tenant default?
Zippy Shell is investing $3,675,000 in the deal as an unsecured subordinated loan. If PackRat defaults and the landlord terminates the lease, that loan is forgiven, resetting the investor capital basis from $292/SF to $260/SF.
How is the acquisition capitalized?
A $22.0M senior loan from Burke & Herbert Bank at SOFR + 1.85% (5-year term, 2 years interest-only), $8.68M of preferred equity, and $3.85M of Class A member equity fund the $34.52M total capitalization.