How you make money
Cash flow
Rent from renovated units, paid out monthly
Assets are bought already occupied and cash-flowing at going-in caps near 7%. Renovation lifts rents from the $600-$850 range toward market, and the resulting income funds monthly distributions.
8.32%
Annual cash yield
Monthly
Distributions
Equity growth
Value created by renovation, realized at refinance
A full unit renovation costs about $13,000 and takes three to five weeks. Higher rents raise NOI and therefore value, which is harvested by refinancing rather than selling, returning capital while the asset is retained.
2.48x
Equity multiple
22%
Projected IRR
5 years
Hold period
Refi
Exit strategy
Tax efficiency
Cost segregation passes depreciation through to you
Each asset sits in its own entity with investors listed as owners. Cost segregation studies accelerate depreciation, so passive losses can offset passive income.
How the deal works
Precision buys occupied, underperforming Class C apartments in the one metro it has run since 2003, typically 100 units or more at $58,000 to $73,000 a door. In-house crews renovate the units and raise rents toward market. That income funds monthly distributions and lifts the asset's value, which is harvested by refinancing rather than selling, so capital returns while the asset keeps paying.
Nine straight quarters of shrinking supply, with 80 units under construction
Tulsa delivered about 1,220 units in 2025, a 49% drop from the 2024 peak, and just 80 units were under construction as of Q1 2026. Absorption of 327 units outpaced 285 delivered, occupancy held at 95.9%, and Class C occupancy sat at 96.0% at $828 a month.
Buying at $58,000 to $73,000 a door while Sunbelt buyers pay far more
The 2025 acquisitions closed between $57,944 and $73,077 per unit against present values of $85,000 or better. Entry cap rates ran from the high 6s to just over 7%, roughly 100 basis points above comparable Sunbelt product.
The same in-house team underwrites, renovates, and manages every asset
Property management, asset management, accounting, and construction management are all in-house across a 40-plus person team. Units turn in two to five days and renovate in three to five weeks, with major materials bought directly to hold cost near $13,000 a unit.
Capital returns at the refinance, then the asset keeps paying
The model is buy, renovate, refinance, hold, not buy and sell. On recent underwriting a $100,000 investment sees roughly $62,500 returned at the refinance while distributions continue, so returned capital can be redeployed into the next acquisition.
Oklahoma's cost base and rules keep workforce demand steady
Oklahoma ranks first nationally for job openings and carries a 7.0% total tax burden, and 68% of residents are priced out of homeownership. There is no rent control, no mandatory grace period, and eviction can be filed and resolved in as little as five days.
About the sponsor
3,200+
Units acquired since 2003
17
Multifamily investments exited
1,163
Units currently held
$116M+
Current portfolio value
Precision Equity Capital Management is a vertically integrated multifamily operator in Tulsa, Oklahoma, founded in 2003 by Victor Whitmore. The firm began with single-family homes in North Tulsa and moved to multifamily in 2006. Property management, asset management, accounting, and construction management are all in-house across a team of more than 40, so the team that underwrites an asset is the team that renovates and runs it. Precision has acquired more than 3,200 units and exited 17 multifamily investments, and holds 1,163 units today.
The 17 exits total 2,060 units, at IRRs in the low-to-mid twenties. Precision reports never having lost investor capital since 2003, across the 2008 downturn, COVID, and the recent rate cycle.
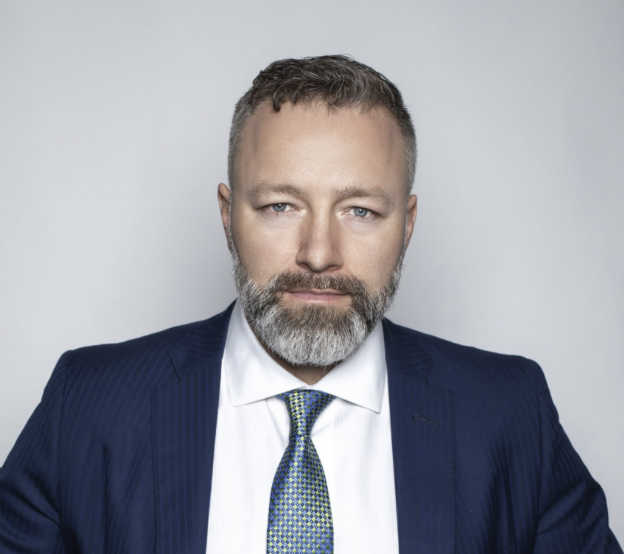
Victor Whitmore
Founder & Managing Partner
Over 20 years acquiring, financing, and operating multifamily in the Tulsa market. Led a portfolio of 3,200-plus units and oversight of more than $250M in total assets. Personally signs and guarantees the debt on every acquisition. Has already built and sold a Tulsa portfolio once and is scaling a second.
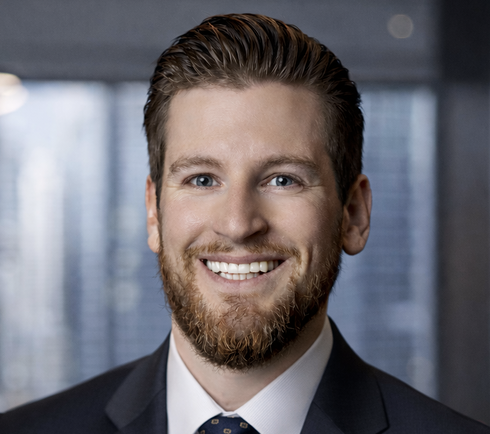
Nicholas Abraham
Director, Capital Markets & Investor Relations
Leads capital formation, investor sourcing, and LP relations for the multifamily platform. Over $250M of deals placed with investors across multifamily, build-to-rent, land, and new construction. Ten years in investor relations, working with more than 5,000 investors.
What you should know
What are the risks?
- Target returns are projections, not guarantees. Past performance does not indicate future results.
- Every asset sits in one metro. A downturn in Tulsa employment would affect the whole portfolio at once.
- Returns depend on renovating units and raising rents on schedule. Slower lease-up compresses distributions.
- The return of capital depends on a refinance. If rates stay high, that refinance and the capital return are delayed.
- This is illiquid. There is no redemption window and no secondary market, so capital should be considered committed.
- Class C workforce housing carries higher tenant turnover and collection risk than newer, higher-income product.
Why Tulsa rather than a higher-growth market?
Entry pricing and supply. The same Class C product trades near $60,000 a door in Tulsa against $220,000 or more in Charlotte, Florida, and Texas, and Tulsa's construction pipeline has contracted for nine consecutive quarters while those markets absorb oversupply.
When does my capital come back?
At the refinance, not at a sale. Recent underwriting returns roughly 62% of invested capital at the refinance in about year three, with distributions continuing after that. Timing depends on rates and on hitting the renovation and rent plan.
What is the track record?
Operating in Tulsa multifamily since 2003, with more than 3,200 units acquired, 17 exits totalling 2,060 units at IRRs in the low-to-mid twenties, and 1,163 units currently under management at a $116M-plus portfolio value.
Who signs on the debt?
Victor Whitmore personally signs and guarantees the loan on each acquisition. Investors never sign. Financing is local bank debt rather than agency or CMBS, and each asset sits in its own entity with investors listed as owners.